What you should know
- Split your money by time horizon: available short term vs. investable long term.
- An emergency fund helps prevent you from having to sell investments at a bad time.
- Higher expected returns always come with higher risk.
- Compare costs, diversification, liquidity and risk — not just past returns.
The right order for investing money
Cover ongoing expenses
Rent, insurance, taxes and foreseeable expenses come first.
Build an emergency fund
Keep a sufficiently liquid reserve for unexpected expenses.
Separate time horizons
Money needed for near-term purchases should not be exposed to stock-market fluctuations.
Choose an investment type
Only now do you compare savings accounts, bonds, ETFs, stocks or other investments that fit the goal.
Review the portfolio regularly
Do not change the plan for every headline, but check whether the goal, risk and allocation still fit.
Saving and investing are not the same
Saving prioritizes availability and capital preservation. Investing accepts fluctuations in order to participate in long-term value growth and returns. Both have a role — just for different time horizons.
A common beginner mistake is treating all money the same. Money for the next holiday has a different risk budget from money with a ten- or twenty-year horizon.
Which investment fits which goal?
For money needed in the short term, safety and liquidity usually come first. With long-term money, an investor may be able to accept more fluctuation. Stocks and equity ETFs can suffer large interim losses, but over the long term they offer different return opportunities from traditional deposits.
The right mix does not depend only on your age. What matters are your goal, time horizon, financial stability and how you actually react during periods of loss.
View a possible mix with Vollat
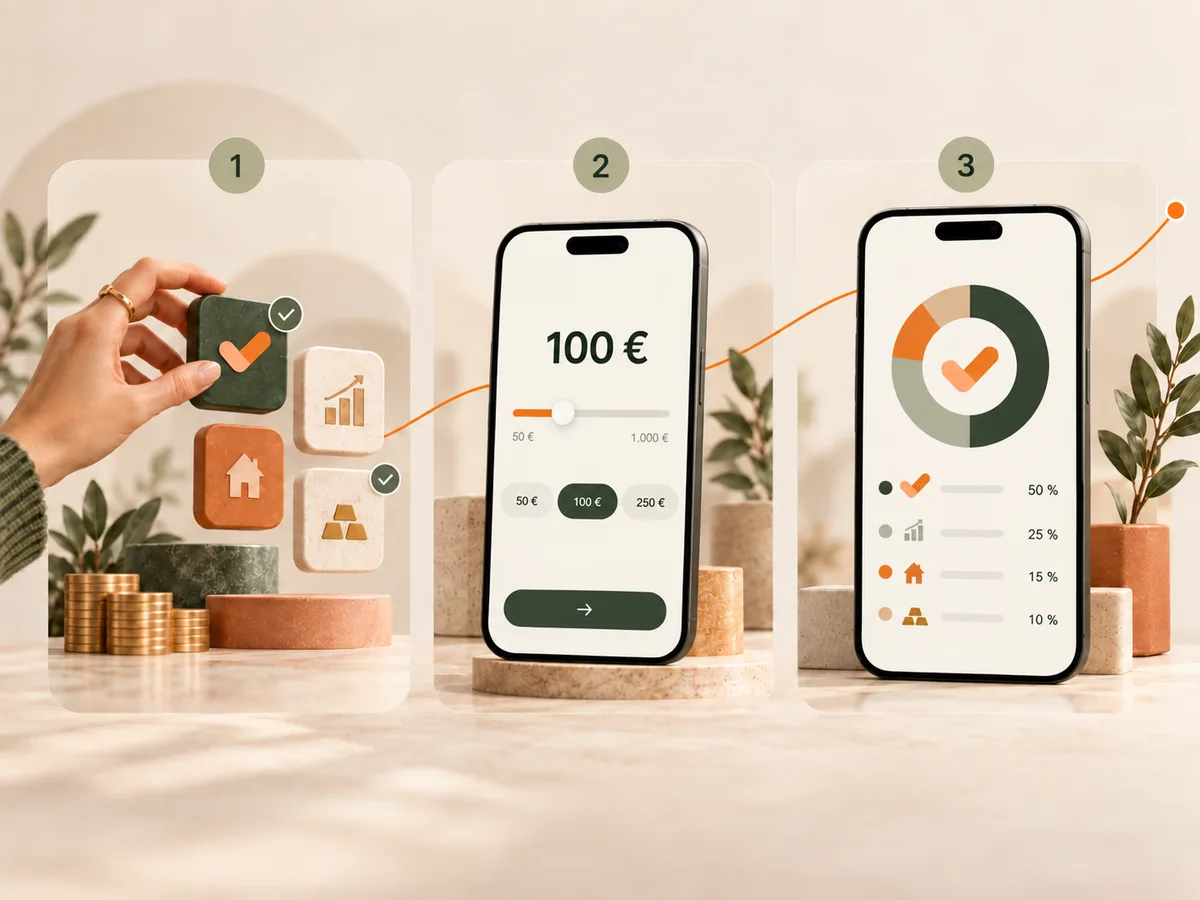
In Vollat, you can choose assets that interest you, enter an amount and select a style. You then see what a possible allocation could look like. This turns an abstract idea into a concrete portfolio you can review.
Vollat does not hold money and does not execute orders. You would still invest through a broker or bank of your choice.
Short answers to common beginner questions
How much should a beginner invest?
There is no universally correct percentage. Invest only the portion of your money that remains available for the long term after ongoing expenses, reserves and short-term goals.
What is better: invest once or contribute monthly?
Both can make sense. A lump-sum investment puts available capital to work immediately; a savings plan spreads contributions over time. What matters are your available capital, costs and how you handle fluctuations.
Which investment has no risk?
Every investment involves risks — for example price, inflation, interest-rate, issuer or liquidity risk. Bank deposits have different protections from securities. High returns without risk do not exist.
What should I read before my first investment?
At a minimum, understand the product, costs, risks, investment horizon and how you can sell again. For securities, also review the provider’s information and independent consumer information.
Independent fundamentals
For financial topics, do not rely on claims from a product page alone. These neutral or public sources are useful for the fundamentals.